The Verkhovna Rada adopted in the second reading and as a whole draft law No. 15111-d on the automatic exchange of information on income received through digital platforms. The document was supported by 241 people's deputies.
If the law is signed by the president, the rules for taxing the income of citizens who earn through online platforms will change in Ukraine. It is about selling goods, renting property, providing personal services, renting transport and other operations through digital services.
In practice, the law may affect users of marketplaces, classifieds services, delivery platforms, taxis, housing rentals, freelance services and other platforms through which individuals receive income.
The main change is that the platforms will have to transfer information about users' income to tax authorities and in a number of cases perform the functions of a tax agent. That is, the tax can be withheld automatically, without a separate declaration by the citizen.
For users, this means the exit of part of the income from the "gray zone". If previously the sale of goods or services via the Internet was often not declared, after the launch of the new mechanism, information about such income will be sent to the tax office.
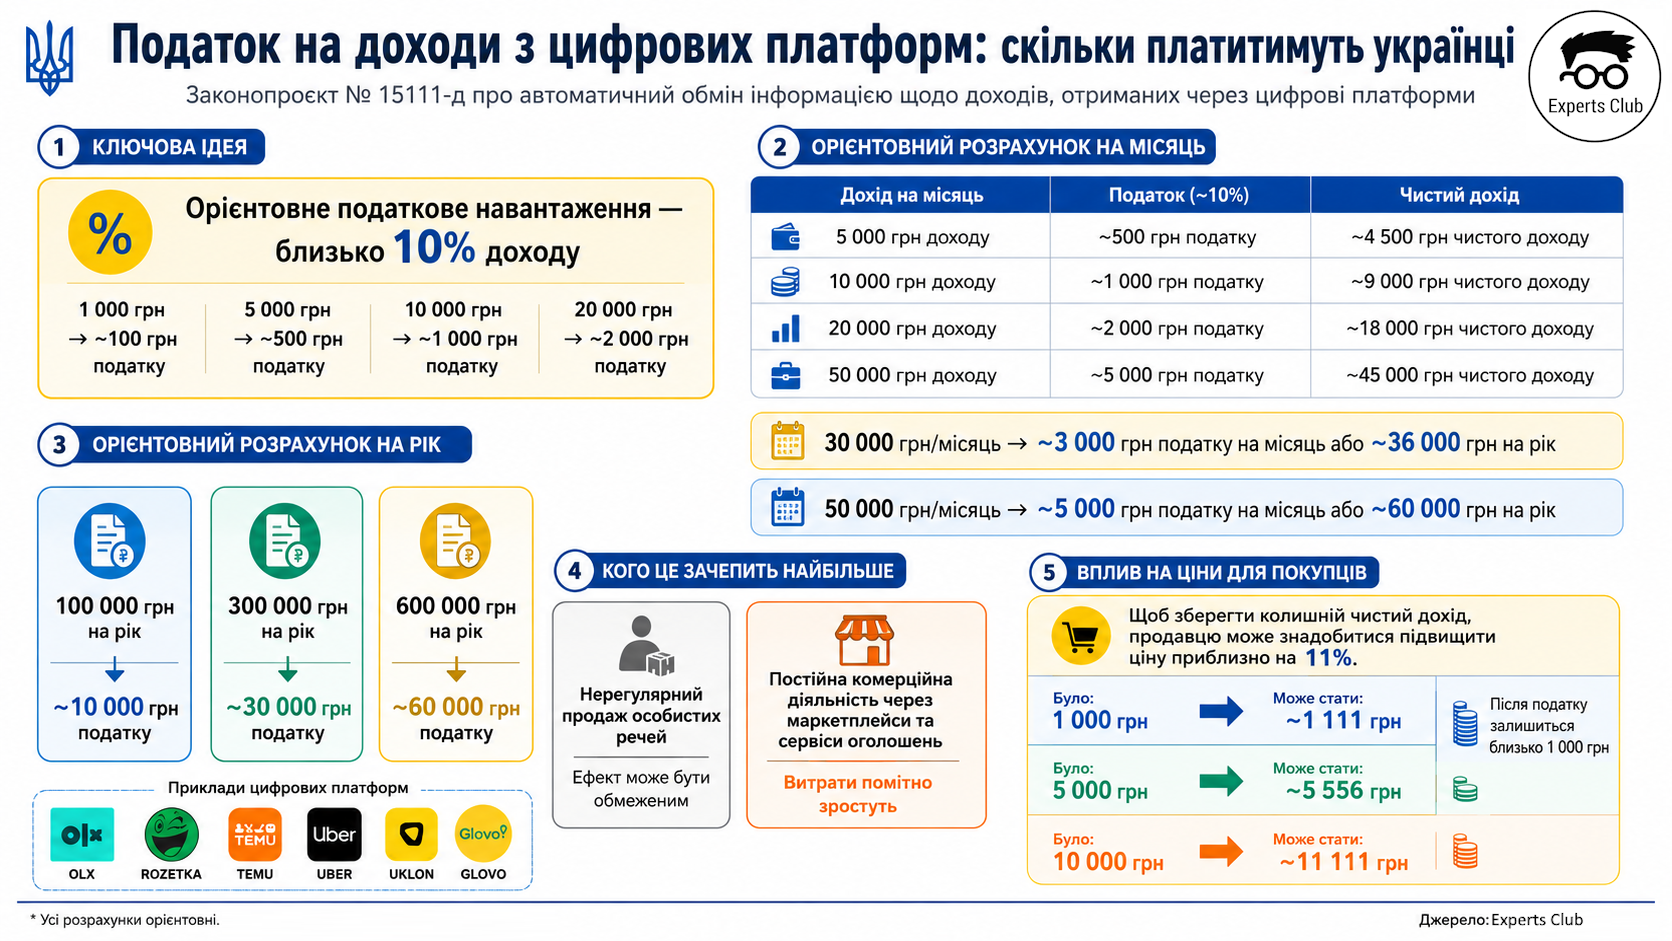
In the final version of the draft law, part of the controversial norms were relaxed. Mandatory opening of special accounts for sellers and regulations on disclosure of bank secrecy were removed from the text. Also, the final version provides for a preferential personal income tax rate of 5% for income through digital platforms. At the same time, taking into account the military levy, the real tax burden for citizens can be about 10% of income.
This means that with an income of UAH 1,000 through the platform, the tax burden can be about UAH 100, with UAH 5,000 - about 500 UAH, with UAH 10,000 - about 1,000 UAH, with UAH 20,000 - about 2,000. UAH.
If a person receives UAH 30,000 per month through the platform, his additional tax expenses may amount to about UAH 3,000 per month, or UAH 36,000 per year. With an income of UAH 50,000 per month, it is about UAH 5,000 per month, or UAH 60,000 per year.
For citizens who sell personal items on an irregular basis, the effect may be limited, but for those who actually conduct permanent commercial activities through marketplaces or ad services, costs will increase significantly.
Approximate calculation:
Income through the platform 5 thousand UAH per month - tax about 500 UAH, net income about 4.5 thousand UAH.
Income 10 thousand UAH per month - tax about 1 thousand UAH, net income about 9 thousand. UAH.
Income 20 thousand UAH per month - tax about 2 thousand UAH, net income about 18 thousand UAH.
Income 50 thousand UAH per month - tax about 5 thousand UAH, net income about 45 thousand UAH.
Income 100,000 UAH per year - tax about 10,000 UAH.
Income 300,000 UAH per year - tax about 30,000 UAH.
Income 600,000 UAH per year - tax about 60,000 UAH.
For buyers, a second effect is possible: some sellers may try to transfer the tax to the price of goods or services. In order to keep the former net income, the seller will have to raise the price by approximately 11%.
For example, if the seller previously wanted to receive UAH 1,000 "net", then withholding 10%, he needs to set a price of about UAH 1,111. Then, after tax, approximately UAH 1,000 will remain.
If the previous price of the service was UAH 5,000, then in order to maintain the same net income, the price may increase to approximately UAH 5,556. For goods or services for UAH 10,000 — approximately UAH 11,111.
However, you should not expect an automatic increase in all prices. In competitive categories, some sellers can take the tax burden on themselves in order not to lose customers. In less competitive segments, the tax is more likely to be partially included in the price.
For the state, the law is important not only as a tax instrument. Its adoption is part of Ukraine's obligations to international partners, including the IMF and the EU. The document is related to the implementation of the international automatic exchange of tax information on income through digital platforms.
For the market, this means increased transparency of online trade and services. For citizens, it is necessary to take into account that income through platforms is gradually ceasing to be "invisible" for the tax authorities.
The main conclusion: the law does not impose a tax on the mere fact of using platforms, but makes income through them controllable. For those who sell goods or provide services on a regular basis, additional costs can amount to about 10% of turnover, if personal income tax and military duty are taken into account. If sellers pass these costs on to customers, final prices could increase by about 10-11%.